

Table of Contents
- Why Physical Bullion Belongs in a Diversified Portfolio
- Gold Portfolio Allocation Percentage: How Much Is Enough?
- Choosing Your Bullion: Coins, Bars, and Collectible Gold
- Gold Bullion Storage Options: Home, Vault, or Custodial?
- How to Verify Gold Bullion Authenticity Before You Buy
- Exit Strategy: Selling, Liquidity, and Estate Planning
- Frequently Asked Questions
Last Updated: September 27, 2026
Why Physical Bullion Belongs in a Diversified Portfolio
Gold bullion is physical precious metal, typically in the form of bars or coins, bought primarily for its metal value rather than its collectible appeal. That distinction matters when you're learning how to build a gold bullion portfolio: you're buying weight and purity, not rarity.
At Parker's Gold, we've watched interest in tangible assets climb as investors look for something they can actually hold. A gold bullion portfolio is the portion of your overall investments allocated to physical gold, whether that's coins, bars, or both.
Bullion earns its place through portfolio diversification. It tends to move independently of stocks and bonds, so it can cushion a portfolio when equity markets turn volatile. Many investors treat it as a safe haven asset and a long-term inflation hedge.
Gold Portfolio Allocation Percentage: How Much Is Enough?
Most financial professionals suggest keeping gold to a modest slice of your total portfolio, often somewhere between 5% and 10%. The right gold portfolio allocation percentage depends on your risk tolerance, time horizon, and how much volatility you can stomach elsewhere.
Gold produces no income. It doesn't pay dividends or interest, so it works best as a stabilizer rather than a growth engine. Investors who overweight it often find their returns lag during strong equity markets.
Sample Allocations by Risk Tolerance
| Investor Profile | Gold Allocation | Primary Goal |
|---|---|---|
| Conservative | 10-15% | Capital preservation |
| Balanced | 5-10% | Diversification |
| Aggressive | 2-5% | Small hedge |
| Speculative | 0-2% | Minimal exposure |
A common mistake is buying gold after a market scare, then selling when stocks recover. Decide your allocation in calm conditions and rebalance on a schedule, not on headlines.
Choosing Your Bullion: Coins, Bars, and Collectible Gold
Bullion coins and gold bars dominate the market for a reason: they're liquid, recognizable, and easy to price against the spot price. Coins like American Eagles and Canadian Maple Leafs carry small dealer premiums and trade readily. Bars, especially one-ounce and ten-ounce sizes, offer lower premiums per ounce but can be harder to sell in partial amounts.
Bullion purity matters here. Investment-grade bullion typically runs .999 fine or higher, and each piece should state its weight in troy ounces. A troy ounce is the standard unit for precious metals, slightly heavier than a standard ounce.
Bullion Coins vs. Numismatic Pieces
Bullion coins are valued for metal content. Numismatic value comes from rarity, age, and condition, and it can far exceed the melt value. If your goal is a gold bullion portfolio grounded in metal weight, stick with bullion. Collectible pieces belong in a separate budget.
U.S. Mint guidance on bullion coin specifications
Gold Bullion Storage Options: Home, Vault, or Custodial?
Gold bullion storage options fall into three camps: home storage, private vaulting, and custodial storage through a dealer or depository. Each carries different costs, access, and risk trade-offs, and the right choice usually comes down to how much metal you hold and how often you need to touch it.
Home Storage
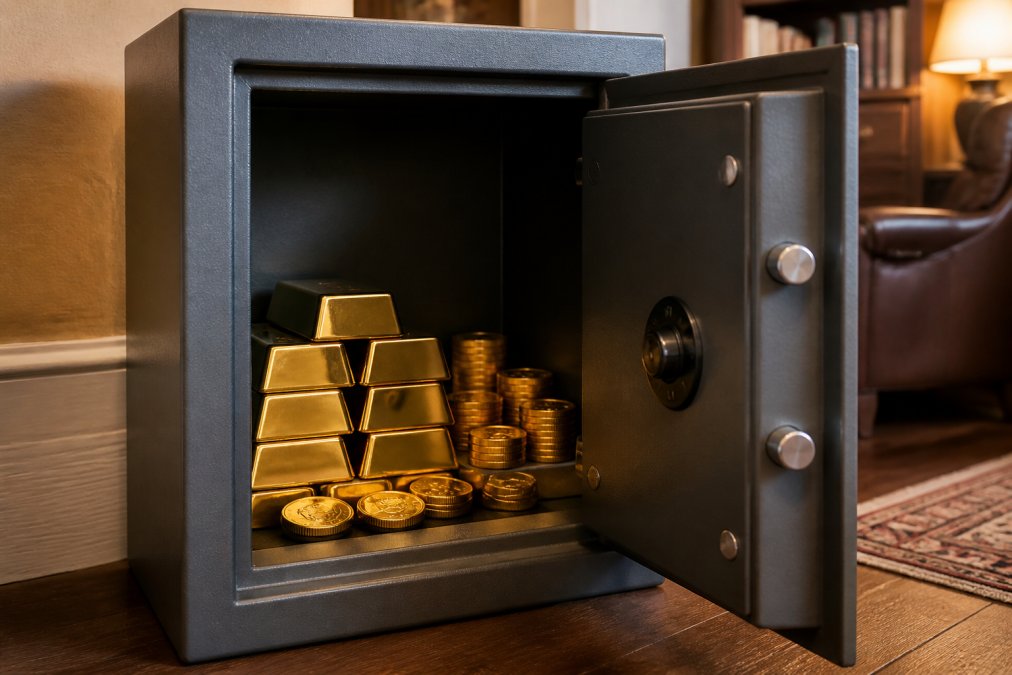
Home storage keeps your gold close and avoids ongoing fees, but it shifts the entire security burden onto you. A quality safe is the baseline. Look for a safe that is bolted to the floor or wall studs, weighs enough that it can't be carried off, and uses a mechanical or electronic lock rather than a keyed lock that can be picked or copied.
Private Vaulting
Private vaulting means a third-party facility stores your metal in a segregated or allocated account, meaning specific bars and coins are titled to you rather than pooled. Segregated storage costs more than pooled storage but gives you clear legal title to identifiable pieces. Facilities typically charge a setup fee plus an annual or monthly storage fee that scales with the value or weight of the holding.
Custodial Storage Through a Dealer or Depository
Custodial storage is convenient for large holdings and for investors who buy and sell frequently, because the dealer can settle trades without physical shipment. The trade-off is that you don't hold the metal directly, and you're relying on the custodian's solvency and record-keeping. Read the custody agreement carefully: it should state whether your metal is segregated or pooled, who carries the insurance, and what happens if the custodian fails.
Insurance and Liability Coverage
Standard homeowners policies often cap coverage for precious metals well below what a serious holding is worth, and the cap is frequently a dollar limit rather than a percentage. A common mistake is assuming you're covered when you're not. Ask your insurer about a scheduled rider or a standalone policy, and keep purchase receipts and appraisals on file.
Matching Storage to Holding Size
A practical rule of thumb: small holdings that you want to access regularly often stay at home in a safe with a rider; mid-size holdings that you rarely touch are often better in a private vault; and large holdings that you trade actively are often best held in custody. There's no single right answer, and many investors use more than one method at once.
How to Verify Gold Bullion Authenticity Before You Buy
Knowing how to verify gold bullion authenticity protects you from counterfeits, which have grown more sophisticated. Start with the basics: weight, dimensions, and the ring of the metal when tapped. A calibrated scale and a set of calipers catch many fakes.
Reading Certificates of Authenticity
A Certificate of Authenticity confirms a piece's origin, weight, and purity. Reputable dealers issue certificates with serial numbers that match the item, and you can often verify them with the issuer. Treat an unsigned or generic certificate as a red flag. When provenance matters, documentation is what separates verified gold from an unverifiable claim.
Exit Strategy: Selling, Liquidity, and Estate Planning
An exit strategy is the plan for converting your bullion back into cash, and it's the part most buyers skip. Bullion is liquid, but the buy-back spread, the gap between what a dealer pays and what they sell for, eats into your return. Expect to sell below spot to a dealer and closer to spot in a private sale.
Where to Sell and What to Expect
There are four common sell-side channels, and each has a different spread and speed:
- Local coin shop or bullion dealer. Fastest and simplest. Expect to sell at or slightly below spot, with the spread widening for odd sizes or obscure brands. Many dealers quote a buy price over the phone before you walk in.
- Online bullion dealers. Often pay closer to spot than a local shop, but you ship the metal first and wait for payment. Insured shipping is standard, and you should confirm who pays for it and what happens if a package is lost.
- Private sale. Usually the closest to spot, but you carry the risk of counterfeit payment, personal safety, and no recourse if the buyer disputes authenticity. Meet in a safe public place or use an escrow service.
- Pawn shops and cash-for-gold outfits. Convenient but typically pay well below spot. Use only as a last resort.
Timing and Tax
Capital gains tax applies to bullion sales, and the holding period matters. Bullion held more than a year is generally taxed at long-term capital gains rates, while shorter holds are taxed at ordinary income rates. Precious metals are also treated as collectibles for tax purposes, which can mean a higher long-term rate than for stocks. Consult a tax professional about your cost basis before you sell, and keep records of every purchase so you can document it.
Inheritance and Estate Planning
If you're drawn to gold for its story as much as its weight, limited-edition pieces sourced from working mines offer something a standard bar can't. Parker's Gold presents raw placer gold flakes from Parker Schnabel's Dominion Creek operation, each package including an official Certificate of Authenticity and a handcrafted tri-fold display case. It's a way to own verified gold with a documented origin, whether you display it or gift it.
Frequently Asked Questions
What percentage of a portfolio should be in gold?
Most financial advisors suggest keeping 5% to 10% of your portfolio in gold, though some investors go up to 15% during periods of high market volatility. The right gold portfolio allocation percentage depends on your risk tolerance, time horizon, and existing exposure to precious metals. Start conservative and adjust as you learn how gold behaves alongside your other holdings.
What are the tax implications of owning physical gold bullion?
Physical gold is treated as a collectible by the IRS, meaning long-term capital gains are taxed at a maximum rate of 28%, higher than the standard 20% long-term rate for most assets. Short-term gains are taxed as ordinary income. Sales of bullion may also trigger reporting requirements depending on quantity. Keep detailed purchase records and consult a tax professional before selling.
How do you store gold bullion securely?
Gold bullion storage options include home safes, bank safe deposit boxes, and professional custodial vaulting services. Home storage gives you direct ownership but carries theft and insurance considerations. Vaulting services charge storage fees but often provide insurance and segregated holdings. Whichever you choose, keep your holdings private and maintain documentation of your purchase for verification and estate planning purposes.
Is gold a good hedge against inflation?
Gold has historically served as a safe haven asset during periods of high inflation and currency weakness, though its performance varies by decade. It tends to hold value over long periods but does not generate income like dividends or interest. Many investors use gold as portfolio diversification rather than a standalone inflation hedge, pairing it with stocks, bonds, and other assets to balance overall risk.
Gold investing rewards patience and preparation more than timing. The investors who do well are the ones who set an allocation, choose products they understand, secure them properly, and plan their exit before they ever need it. Parker's Gold helps collectors start that relationship with gold through authenticated, mine-sourced pieces, fully insured and tracked shipping, and documentation that stands up when provenance matters. Claim yours and own a piece of the North.