

Table of Contents
- What Makes Raw Gold a Potential Inflation Hedge
- Gold Bullion vs Raw Gold: Which Offers Better Inflation Protection?
- Historical Performance: Gold Prices During Inflationary Periods
- The Benefits of Holding Physical Gold in an Inflationary Environment
- Taxes, Storage, and Liquidity: The Real Costs of Raw Gold
- How to Store Raw Gold Safely
- Pros and Cons of Raw Gold as an Inflation Hedge
- Conclusion: Is Raw Gold Right for Your Portfolio?
- Frequently Asked Questions
Last Updated: September 22, 2026
What Makes Raw Gold a Potential Inflation Hedge
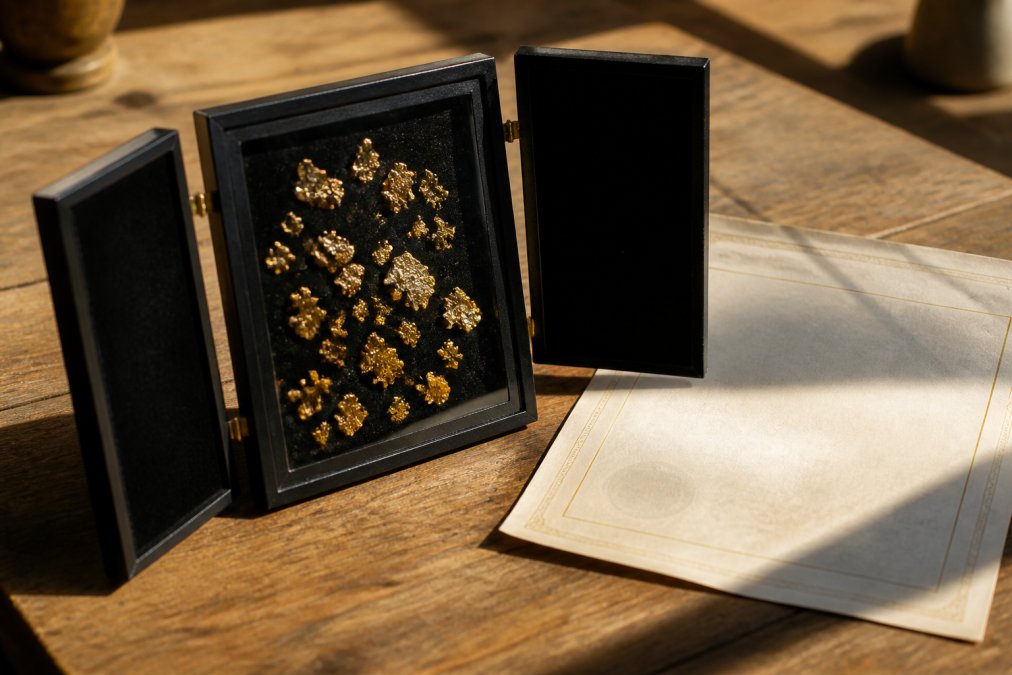
Raw gold is unrefined gold in its natural state, placer flakes, dust, or nuggets, and it hedges inflation because its supply cannot be expanded at will the way a fiat currency can. Central banks can print more dollars; they cannot print more gold.
This guide from Parker's Gold examines whether that thesis holds up in practice, where it breaks down, and what the real costs of ownership look like. Inflation erodes purchasing power. When the dollar loses value, assets priced in dollars tend to rise, and gold has historically been one of the assets that moves with that devaluation. The Federal Reserve's inflation guidance explains how the Fed measures and targets inflation, which matters because gold's behavior tracks monetary policy more than it tracks headline price increases.
Raw placer gold, minted bullion, and gold ETFs behave differently because of how they're bought, stored, and sold.

Gold Bullion vs Raw Gold: Which Offers Better Inflation Protection?
Raw gold and bullion track the same spot price, so both hedge inflation similarly in percentage terms. The difference is premiums, purity, liquidity, and resale ease.
Bullion is refined to a known purity, usually 99.5% or higher, and stamped with a recognized mark, making it easy to price and sell. Raw gold varies in purity and must be assayed before a dealer quotes a firm price, appealing to collectors, but a friction cost for pure hedging.
Raw gold wins on scarcity and provenance: a verified raw placer flake from a documented operation carries value beyond its melt weight. Bullion wins on spread: a one-ounce American Gold Eagle trades close to spot, while raw gold sells at a premium and resells at a discount.
A common mistake is assuming a higher premium means a better hedge. It doesn't, premiums are collectible value, not inflation protection.
Historical Performance: Gold Prices During Inflationary Periods
Gold's record during high-inflation stretches is mixed. The pattern most guides miss: gold responds not to the inflation rate itself but to real interest rates, the nominal Treasury yield minus inflation. When real rates go negative, gold tends to do well; when they are positive and rising, gold struggles even if headline inflation is high.
Demand-Pull vs. Cost-Push Inflation: Why the Type Matters
Gold reacts differently depending on which kind of inflation is driving prices.
Short-Term vs. Long-Term: Two Different Assets
Over short horizons, a year or two, gold is volatile and largely unpredictable, falling during some inflation spikes and rising during calm periods. Anyone using gold as a 12-month inflation trade takes on significant timing risk.
The Benefits of Holding Physical Gold in an Inflationary Environment
Physical gold is an asset you hold outright, with no counterparty risk, the benefit most often undersold. An ETF or futures contract depends on an institution honoring its obligation. Physical metal does not.
The benefits of holding physical gold come down to four things:
- No counterparty exposure, since you own the metal directly
- Tangible scarcity, because annual mine supply is small relative to above-ground stock
- Global liquidity, since gold trades in every major market
- Currency independence, because gold is priced in dollars but valued worldwide
Taxes, Storage, and Liquidity: The Real Costs of Raw Gold
Most gold guides skip the three costs that decide whether a hedge actually pays off: taxes, storage, and the bid-ask spread. All three eat into returns, and all three are larger for raw gold than for bullion.
Taxes: The Collectible Rate Changes the Math
The IRS treats physical gold as a collectible, not as a standard capital asset. That distinction matters because long-term capital gains on collectibles are taxed at a higher maximum rate than long-term gains on stocks, bonds, or most ETFs. The IRS guidance on collectibles and capital gains spells out which assets fall into that category.
Parker Schnabel Yukon Gold Flakes →
What that means in practice:
- Short-term gains (held one year or less) are taxed as ordinary income, at your marginal rate.
- Long-term gains on physical gold are taxed at the collectibles rate, which is higher than the standard long-term capital gains rate applied to securities.
- Gold ETFs structured as grantor trusts are generally treated the same as physical metal, they do not get the standard securities rate, a detail most guides omit.
- Mining stocks are typically treated as equities and can qualify for standard capital gains rates, but you are then holding a company, not metal, with the operational and market risk that implies.
Storage: The Cost That Compounds
Storage is an ongoing expense that accumulates every year you hold the metal, directly reducing your net hedge. You have three real options:
| Storage Method | Typical Cost Structure | Best For | Main Risk |
|---|---|---|---|
| Home safe or vault | One-time equipment cost, plus optional rider on homeowner's policy | Small holdings, frequent access | Theft, fire, insurance gaps |
| Bank safe deposit box | Annual rental fee | Moderate holdings | Limited access hours, box contents not insured by the bank |
| Third-party depository | Ongoing storage fee plus insurance, billed annually | Large holdings | Counterparty risk and fee drag |
Liquidity: The Spread Is the Silent Cost
Raw gold is the least liquid of the three forms, raw, bullion, and ETF, and the spread is where that shows up.
Putting the Three Costs Together
To evaluate raw gold as an inflation hedge, subtract all three costs from the inflation rate you are trying to offset:
- Spread, the round-trip friction between buy and sell price.
- Storage and insurance, the annual carrying cost.
- Taxes, the collectible rate applied to your gain at sale.
How to Store Raw Gold Safely
Storing raw gold safely means protecting it from theft, physical damage, and loss of provenance. The third is unique to raw gold and the one most people ignore.
For the gold itself:
- Keep small holdings in a home safe bolted to the floor, not a portable lockbox
- Use a bank safe deposit box for moderate holdings, and confirm what your homeowner's policy actually covers
- Choose a third-party depository for large holdings, and read the insurance terms line by line
- Never store gold and its documentation in the same place
Pros and Cons of Raw Gold as an Inflation Hedge
Raw gold works as an inflation hedge in specific conditions and underperforms in others. The honest answer depends on your horizon and your reason for buying.
Pros:
- No counterparty risk, since you hold the metal directly
- Tangible scarcity that no central bank can dilute
- Collectible premium on verified, documented pieces
- Global liquidity and universal recognition
Cons:
- Higher premiums and wider resale spreads than bullion
- No yield, so a real opportunity cost in high-rate environments
- Collectible tax treatment with higher long-term capital gains rates
- Storage and insurance costs that compound over time
- Purity uncertainty, since raw gold requires assay before a firm quote
Conclusion: Is Raw Gold Right for Your Portfolio?
Raw gold is a reasonable inflation hedge for investors who want tangible, counterparty-free assets and can tolerate the premium, spread, and storage costs. It's a poor choice for anyone chasing short-term returns or needing liquidity on demand. Investors who do well buy for the long term and treat the collectible premium as a bonus, not the point.
Frequently Asked Questions
Does gold actually protect against inflation in the long term?
Gold has preserved purchasing power over very long periods, but its short-term record is mixed. During the 1970s inflation spike, gold prices rose sharply. In other inflationary periods, such as the 1980s and 1990s, gold lagged behind inflation. Research from institutions like the World Gold Council shows gold's correlation with the Consumer Price Index varies by time frame. Raw gold works best as a long-term store of value within a diversified portfolio, not as a guaranteed short-term inflation hedge.
What is the difference between raw placer gold and gold bullion?
Raw placer gold is natural gold recovered from streams and gravel deposits, often in flake or nugget form. It has no standardized purity or weight, so each piece is unique. Gold bullion is refined to 99.5% or higher purity and stamped with weight and fineness by a mint or refiner. Bullion trades at prices close to the spot market, while raw gold's value depends on authenticity, provenance, and collector demand. For pure inflation hedging, bullion's standardized pricing makes it easier to buy and sell.
Is raw gold considered a liquid asset for inflation protection?
Raw gold is less liquid than gold bullion or gold ETFs. Bullion dealers and exchanges buy and sell standardized bars and coins daily at published spot prices. Raw placer gold requires authentication, assay, and often a specialized buyer, which adds time and cost to any sale. If you need to convert your holdings quickly during an inflationary spike, raw gold's illiquidity can work against you. Collectors who value provenance may pay more, but the buyer pool is smaller.
Are there tax implications for holding raw gold as an asset?
Yes. The IRS classifies physical gold, including raw gold and bullion, as a collectible. Long-term capital gains on collectibles are taxed at a maximum rate of 28%, higher than the 20% maximum for most long-term investments. Short-term gains are taxed at ordinary income rates. Sales may also trigger 1099-B reporting depending on the transaction size. Consult a tax professional before buying or selling raw gold to understand your specific obligations.